
EveryDollar: Budget Management
- Rating
- 4.3
- Downloads
- 1.00M
- Content Rating
- Everyone
EveryDollar: Budget Management - Screenshots
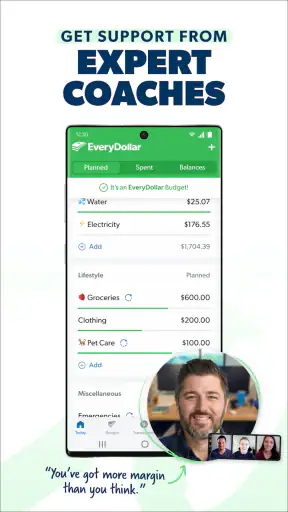
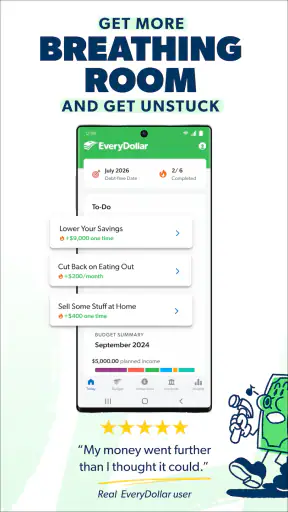
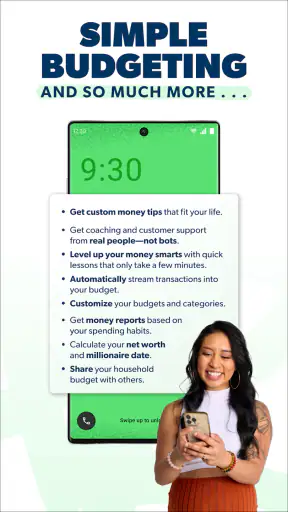
Pros
- Simple zero-based budgeting makes every dollar easy to assign.
- Clean interface helps users review spending without feeling overwhelmed.
- Custom budget categories can be tailored to different financial goals.
- Syncing across supported devices keeps budgets accessible on the go.
- Useful for couples who want a shared view of household finances.
Cons
- Automatic transaction importing requires a paid Premium subscription.
- Bank connections may occasionally need to be refreshed or reauthorized.
- Limited investment and net-worth tracking compared with broader finance apps.
- Users must enter cash purchases manually to keep totals accurate.
- Some advanced budgeting features have a learning curve for beginners.
EveryDollar: Budget Management - Description
- App Name
- EveryDollar: Budget Management
- Package Name
- com.everydollar.android
- Developer
- Ramsey Solutions
- Category
- Finance
- Last Updated
- Jul 10, 2016
- Version
- 2026.8.260
I approached EveryDollar as a practical budgeting tool rather than a general banking app, and that distinction matters. It is a finance app from Ramsey Solutions built around giving your income a job before the month gets away from you. The basic idea is simple: plan where your money should go, then compare that plan with what actually happens.
That simplicity is the main reason I can see people sticking with it. Many finance apps try to show everything at once—accounts, investments, bills, credit information and spending charts. EveryDollar focuses more narrowly on the budgeting decision itself. If your biggest problem is not knowing how much is safe to spend, that focused approach feels more useful than a crowded financial dashboard.
The app is free to install and is rated for Everyone, so it is approachable for households that want to start budgeting without committing money upfront. It has built a substantial audience, with over a million installs and an average rating of 4.3 from around 15 thousand ratings. Those figures do not guarantee that it will suit every budget, but they do suggest that the basic method is understandable to a wide range of users.
How the free and paid value is divided
The cost question deserves a careful distinction. EveryDollar is free to download, while in-app purchases range from $7.99 to $129.99 per item. That means you can begin using the app without paying for access, but some of the more advanced value sits behind optional purchases. I would not treat the free download as proof that every capability is included at no cost.
For someone testing a budgeting method, the free entry point is a real advantage. You can decide whether assigning income to categories fits the way you think before spending anything. That is especially helpful if you are moving from a notebook, spreadsheet or vague mental estimate of your finances. The paid range is broad enough that I would check the exact offer shown in the app before buying, rather than assuming a particular plan or price.
In practical terms, the free experience is most valuable when you are willing to enter transactions and review the plan yourself. Manual involvement can feel slower than automatic tracking, but it also makes each purchase harder to ignore. A coffee, subscription or unplanned online order becomes part of the budgeting conversation instead of disappearing into a monthly total.
Paid value makes more sense for people who want less manual work or who already believe in the EveryDollar approach and expect to use it consistently. I would avoid paying immediately just because the app looks polished. First, create a realistic month, include irregular expenses and see whether the routine helps you make decisions. If it does, a paid option may be easier to justify; if it does not, paying will not fix a budgeting method that does not fit your habits.
What the app is trying to change
The central benefit is not a colorful spending chart. It is the shift from asking, “Where did my money go?” to asking, “What should this money do before I spend it?” That small change can be powerful for people whose income is adequate but whose spending feels unplanned.
I found the approach especially useful for separating fixed commitments from flexible choices. Rent, utilities and debt payments need space in the plan, but groceries, entertainment and shopping can easily expand when they are not given boundaries. Putting those decisions into categories makes trade-offs visible earlier, when there is still time to adjust.
The app also suits a household conversation better than a private collection of bank alerts. Partners can discuss priorities using the same plan: whether to reduce restaurant spending, protect a savings goal or deal with an unusually expensive month. That does not remove disagreements, but it gives the discussion something more concrete than memory and guesswork.
A realistic month with EveryDollar
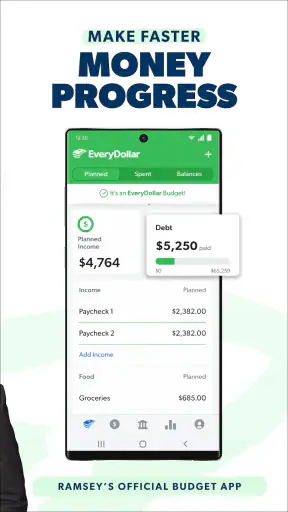
Imagine I receive my regular income near the start of the month. Instead of treating the whole amount as available, I first assign money to housing, utilities, food, transportation, insurance and required payments. I then make room for flexible spending and less frequent costs, such as gifts, annual renewals or car maintenance.
Midway through the month, groceries cost more than expected. The useful response is not to pretend the original number was accurate. I can reduce another flexible category, move money between categories and keep the overall plan balanced. That moment is where a budgeting app earns its place: not when everything goes perfectly, but when it helps me make a deliberate correction.
At the end of the month, I would look for categories that repeatedly miss their targets. If food is always too low, the answer may be to set a more realistic amount rather than repeatedly marking the plan as a failure. If entertainment regularly consumes money intended for savings, the pattern becomes visible enough to address. This is a more constructive workflow than simply feeling guilty about overspending.
Useful habits that are easy to overlook
One of the smartest ways to use EveryDollar is to budget for non-monthly expenses before they become emergencies. A yearly bill can be divided into smaller monthly amounts, and a future repair can be treated as a planned responsibility rather than an unexpected disaster. This requires discipline, but it turns irregular costs into something the monthly plan can absorb.
A second useful habit is to review the budget before making a purchase, not only afterward. If I am considering a new jacket or a larger grocery trip, the relevant question is whether that category has room. This turns the app into a decision tool instead of a record-keeping chore. The difference may sound minor, but it changes when the app enters the spending process.
A third insight is to avoid creating too many categories at the beginning. It is tempting to divide every type of purchase into a very detailed structure, but excessive detail can make daily updates tiring. I would start with categories that lead to real decisions, then split them only when a combined total hides a recurring problem. A budget that I maintain is more useful than a perfect one I abandon.
It is also worth giving the plan a short weekly review rather than waiting for the month to end. I would check the remaining amounts, account for recent purchases and move money where priorities have changed. This keeps small mistakes from becoming a dramatic end-of-month surprise and makes the app feel like an ongoing routine rather than a financial autopsy.
Where the focused design helps—and where it creates friction
The strength of deliberate budgeting
EveryDollar’s focused design is its clearest advantage over many alternatives. A typical bank app is good at showing transactions, balances and account activity, but it may not help me decide how much I should reserve for each purpose. A spreadsheet can do almost anything, but I have to build and maintain the system myself. EveryDollar sits between those options: more structured than a blank spreadsheet and more intentional than a transaction feed.
That makes it a strong fit for beginners who need a method, not just information. The category-based plan gives each expense a place and encourages me to deal with the entire income amount rather than budgeting only the bills I remember. It can also help experienced budgeters who want a dedicated routine without designing formulas and tabs from scratch.
The trade-off is that the app asks for participation. People who want their finances to organize themselves automatically may find the process demanding, particularly during busy weeks. Manual attention can be a benefit when it builds awareness, but it is still a cost in time and effort. I would not recommend it to someone who strongly dislikes entering or reviewing financial activity.
How it compares with common alternatives
Compared with a spreadsheet, EveryDollar is less flexible but easier to approach. A spreadsheet can be customized for unusual income, complex reimbursements or detailed forecasting. It can also be shared and modified in ways that suit a particular household. The app’s advantage is that the budgeting workflow is already shaped around personal spending decisions, so I do not need to invent the structure first.
Compared with a bank’s built-in budgeting tools, EveryDollar puts more emphasis on a forward-looking plan. Bank tools often excel at reporting what has already happened. That is useful for checking activity, but it does not always create the same pressure to assign money before spending it. If I mainly need account monitoring, my bank may be enough. If I need a deliberate monthly plan, this app is more relevant.
Compared with a highly automated finance tracker, EveryDollar can feel less effortless. Automation reduces the work of collecting transactions and can be convenient for people with many accounts. The downside is that automatic categorization may make spending feel distant or occasionally misclassified. EveryDollar’s more hands-on style is better for learning where money is going, but worse for someone who values near-zero maintenance above all else.
Compared with a debt-focused or investment-focused app, this is a broader household budgeting starting point. It can help create room for those goals, but I would not choose it solely because I want specialized portfolio analysis or an advanced debt calculator. Its value is in coordinating everyday money, not replacing every financial tool a person might eventually need.
Friction I would plan for
The first friction is consistency. A budget only reflects reality when purchases and changes are kept current. Missing several days can make the numbers feel unreliable, and catching up may be unpleasant if there are many transactions. I would schedule a regular review and keep the first version of the budget simple enough to maintain.
The second is emotional rather than technical. A category that is too restrictive can make normal spending feel like failure. The better approach is to use the app to reveal priorities and make trade-offs, not to create an impossible standard. If the plan repeatedly breaks in the same area, I would revise the plan and investigate the habit instead of merely resetting the number.
The third concerns the paid decision. Since optional purchases span a wide range, the app’s value depends on what is included in the specific option presented to me and how much work it removes. I would compare that benefit with my actual routine. Paying for features I rarely use is poor value, while paying for a workflow that I genuinely maintain can be reasonable.
The app is also not the right answer for every financial situation. Someone managing a business, multiple currencies, complicated shared expenses or detailed investment reporting may need a more specialized product. Likewise, a person who already has a reliable spreadsheet and enjoys maintaining it may gain little from changing systems. EveryDollar is strongest when the problem is everyday household planning, not advanced financial administration.
Who is most likely to get real value?
I would recommend EveryDollar first to people who earn income regularly but still reach the end of the month wondering why so little remains. It is also a sensible option for couples who need a shared language for spending decisions, parents trying to make room for irregular family costs and beginners who want more guidance than a blank spreadsheet provides.
It can be particularly useful during a transition: moving into a new home, paying down obligations, adjusting to a different income or trying to stop relying on credit for ordinary expenses. In those situations, the benefit comes from making the full set of commitments visible and deciding what can change before money is spent.
I would be more cautious about recommending it to someone whose main requirement is automatic account aggregation. If the person will not review categories, adjust the plan or record spending, the app may become another unused download. The same is true for people who want a detailed financial command center covering investments, taxes and business activity. A narrower tool can be excellent, but only when its narrowness matches the problem.
New users should begin with one ordinary month rather than trying to design a lifelong financial system on the first day. Add the obvious obligations, estimate flexible spending honestly and include at least a few expenses that do not arrive every month. After using the plan, revise the categories based on actual behavior. That learning cycle is more valuable than chasing an ideal budget immediately.
Families should also agree on who updates the plan and how purchases are communicated. A shared budget can fail when one person assumes the other is recording everything. Even a simple arrangement—one person updates it on a chosen day and both people check the flexible categories—can prevent confusion. The app can support the conversation, but it cannot create shared responsibility by itself.
My verdict on paying, trying and skipping
EveryDollar is worth trying if you want a clear, category-based budgeting routine and are prepared to participate in it. The free access lowers the risk of testing the method, while the optional paid purchases create a second decision that should be based on actual use rather than curiosity. I would start free, build a realistic month and judge the app by whether it changes my spending decisions.
The strongest value is behavioral. The app encourages me to plan before spending, notice repeated problems and make trade-offs while there is still room to act. That is more meaningful than a dashboard that merely reports yesterday’s transactions. Its weakness is the same: the results depend on regular attention, and people seeking completely automatic tracking may become frustrated.
Ramsey Solutions has kept the product in the finance category since its release on July 10, 2016, and the current version is 2026.8.260 for devices running Android 7.0 or later. Those details make it a practical option for many Android users, while the Everyone age rating keeps its intended audience broad. I would still treat compatibility and the exact purchase screen as part of the installation decision.
My recommendation is simple: try the free experience if your problem is unplanned everyday spending, but skip it if you want a fully automatic tracker or specialized financial analysis. For the right user, the app’s value is not that it magically saves money. It gives each amount a purpose and makes the consequences of a choice easier to see. If you are willing to keep that plan alive, it can become a useful financial habit rather than just another place to view numbers.
FAQ
What is EveryDollar: Budget Management, and how does it work?
EveryDollar is a zero-based budgeting app designed to help you plan where your income will go before you spend it. After entering your expected monthly income, you assign amounts to categories such as housing, groceries, transportation, bills, savings, and entertainment. As you record transactions, the app shows how much remains in each category, making it easier to monitor spending and stay aligned with your financial goals.
Is EveryDollar free to download and use?
EveryDollar can generally be downloaded for free, and its basic version provides the essential tools for creating a monthly budget and manually tracking transactions. However, some advanced features may require a paid subscription, depending on the current plan offered in your region. Before subscribing, review the in-app pricing, renewal terms, and included features to decide whether the premium version provides enough value for your budgeting habits.
Does EveryDollar connect to bank accounts automatically?
Bank connectivity is typically associated with EveryDollar’s paid features, while the free version is primarily designed for manual transaction entry. If automatic importing is available for your account and financial institution, it can reduce the effort required to keep your budget updated. Compatibility may vary, so users should check whether their bank is supported and review how securely account information is handled before connecting it.
Can EveryDollar be used by couples or families?
EveryDollar can be useful for couples and families because it provides a shared structure for planning income, bills, savings, and everyday spending. Its effectiveness depends on how consistently everyone records purchases and communicates about the budget. Before relying on it for household finances, check the current subscription and sharing options, since collaboration features and account access may differ between the free and paid versions.
Is EveryDollar suitable for beginners who have never budgeted before?
Yes, EveryDollar is particularly approachable for beginners because its zero-based budgeting method gives each dollar a specific purpose. The category-based layout is straightforward, and users can begin with common expenses before adding more detailed goals. New users should expect to spend some time estimating irregular costs and updating transactions regularly, since the app is most helpful when the budget reflects real spending rather than remaining only a monthly plan.


